Mortgage rates are the highest in nearly three years. Here’s what that changes about buying a Florida rental building — in plain numbers.
FL Real Estate Insider — Week of October 5, 2026
By Luis Noronha
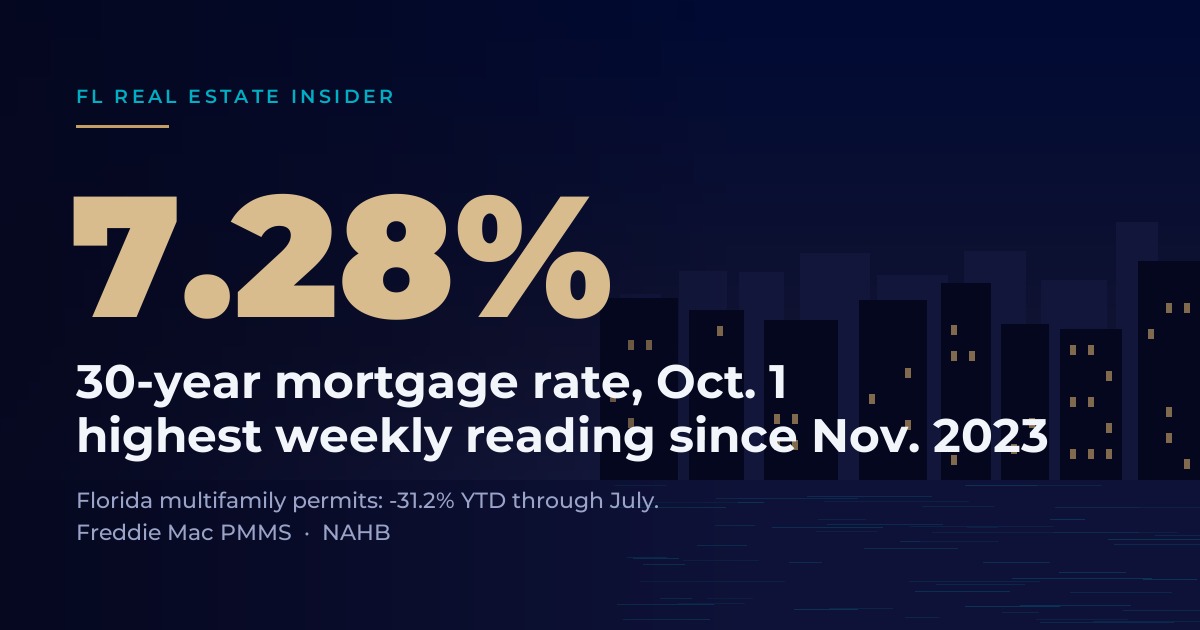
7.28%. That was the average 30-year fixed mortgage rate on October 1, according to Freddie Mac, the government-sponsored company that buys home mortgages from lenders — up from 7.03% a week earlier and 6.34% a year ago. (Freddie Mac — Mortgage Rates Average 7.28%, October 1, 2026) The last week it was higher was November 22, 2023, at 7.29%. (Freddie Mac’s weekly rate history)
The highest in nearly three years.
One caveat: that’s a home-loan rate, and loans on apartment buildings are priced differently. I use it because it comes out every week, which makes it the easiest way to track borrowing costs since the Fed’s unanimous rate hike on September 16.
Why expensive loans change the math
Here’s the math with made-up numbers, so it’s easy to follow. This is an illustration, not market data.
Say you buy a small rental building for $2 million. After all expenses except the mortgage, it brings in $120,000 a year. That’s a 6% return on the price.
You put in $600,000 of your own money and borrow $1.4 million at 7%. To keep it simple, count only the interest: $98,000 a year. What’s left for you is $22,000 — a 3.7% return on your $600,000.
You’d have earned more paying cash.
That’s the trap. When a building earns less than its loan costs, borrowing doesn’t boost your return. It shrinks it. At 5%, the same loan would cost $70,000 a year and leave you $50,000 — 8.3% on your cash.
Opinion, clearly marked: at today’s rates, buying a Florida rental just for the income it already makes usually means the bank earns more from the building than you do. So the better question this fall isn’t “what does this building earn?” It’s “what could it earn?”
The income you buy vs. the income you build
CBRE, one of the largest commercial real estate firms, measures a building’s return two ways in its twice-yearly survey. (CBRE — U.S. Cap Rate Survey H1 2026) In plain terms:
- The income you buy: what the building earns running normally, before any improvements, divided by the price you pay.
- The income you build: what it earns after you improve it, divided by the price plus what you spent improving it.
The industry calls the second approach “value-add” — adding value by fixing things.
Back to the example. Suppose you spend $200,000 fixing the building: rents raised to what similar units get, service contracts like landscaping and trash shopped around, empty units filled. Its income after expenses rises to $170,000. Now the math is $170,000 ÷ $2.2 million = 7.7%, above what the loan costs. Same building, run better. (Again: made-up numbers.)
That’s the point of this issue. In my view, at today’s rates only the income you build can carry a loan.
Prices are already moving. CBRE found that in the first half of 2026, the price paid for each dollar of a building’s income went up more for mid- and lower-tier buildings and fixer-uppers than for top-tier, stable ones. (CBRE) That covers all property types, not just apartments, and CBRE says it likely reflects ups and downs (volatility) for buildings with less certain income. Either way, my read is that fixer-uppers cost more per dollar of income than they did.
Where the fixable buildings are
Here’s the part I rarely see in the rate headlines: who owns the building.
A 2024 government survey by HUD, analyzed by the National Multifamily Housing Council (NMHC), shows how ownership changes with building size. Individual investors — people, not companies or funds — own 19.2% of rental homes in properties with 5 to 24 units. In properties with 25 to 49 units, it’s 5.7%. In properties with 50 or more, 4.6%. (NMHC — Who Owns America’s Apartments?, March 24, 2026)
Professional management shows a similar pattern. HUD’s 2021 survey found that about 22% of the smallest rentals (one to four units) are run by professional managers, compared with 84% of properties with 150 or more units. (HUD — 2021 Rental Housing Finance Survey findings) The survey’s headline numbers don’t cover the sizes in between, so I won’t guess.
My interpretation, not data: the smaller the building, the more likely its owner runs it personally. That doesn’t mean badly. But it’s where you’re most likely to find rents below market, bills nobody has shopped around in years, and repairs that keep getting put off. That’s exactly what a good manager can fix.
To be fair, the NMHC author, Chris Bruen, is careful here. On whether the type of owner changes rents, he writes that “relatively little empirical research has been conducted on this topic to date” — in other words, it hasn’t been studied much. My read goes further than the evidence, and I’d rather say so.
Florida is permitting fewer new competitors
In August I argued that the housing shortage favors new construction, and last week I said I still do. Here’s what the same shortage means for a building that’s already standing.
First, almost all new homes in multi-unit buildings go into big buildings. Of the 608,000 new homes the U.S. finished in 2024 in buildings with two or more units, 90.1% were in buildings with 20 or more units and 2.7% in buildings with two to four. (NMHC) That leaves 7.2% for everything from five to 19 units — my math, not NMHC’s.
Second, Florida is pulling back. In the first seven months of 2026, the number of new homes permitted in Florida in buildings with two or more units fell 31.2% from a year earlier, while nationally that number rose 6.3%. (NAHB Eye on Housing, September 15, 2026) And building costs more: prices of residential building materials, not counting energy, were up 5.1% from a year earlier in August. (NAHB Eye on Housing, September 10, 2026)
My view: fewer new buildings, and higher costs to build them, both help a well-run existing building. Neither guarantees higher rents. A drop in permits today shows up as fewer finished buildings only later, and a weak rental market can outlast a building slowdown.
Four ways I think a fixer-upper deal goes wrong
This is not free money.
You overpay for the upside. If sellers already price in what the building could earn, you’ve paid for the improvement before you’ve done it.
The sale price can move against you. In CBRE’s survey, its own real estate professionals were gloomiest about lower-quality (class C) buildings: they expect buyers to pay less for each dollar those buildings earn over the next six months. They were also most pessimistic about “infill” apartments, in areas that are already built up. (CBRE) A plan that assumes you’ll sell at today’s prices is assuming that risk away.
Fixing takes time and money. Every month of renovation is a month of loan payments.
Some costs aren’t yours to fix. Insurance, property taxes and major repairs don’t care how well you run the building. The income you build has to cover those bills too.
And, in my view, taxes won’t rescue a bad deal. As I wrote last week, a tax rule called 100% bonus depreciation is now permanent. It lets you write off certain parts of a building right away instead of over many years, and it can apply to existing buildings. My rule hasn’t changed: it makes a good deal better. It doesn’t make a money-losing deal work.
My five questions before you buy a small Florida rental building
These are my questions, not investment or tax advice.
- Does the building earn more than the loan costs? If not, the loan is shrinking your return until you fix something.
- What exactly is broken? Rents, expenses, empty units, unpaid rent, management — list it line by line. “Upside” isn’t an answer.
- What will it earn after the fix? Divide that by the price plus what the fix costs — not by the broker’s number.
- Does the deal still work without the tax break? If not, you’re buying a tax break, not a building.
- What will a buyer pay you when you sell? If you’re assuming today’s price, ask why.
From the Developer’s Seat
Opinion from here down: how this looks from where we build.
At Lana we build homes to sell, and I’ve always started with what a buyer will pay for the finished home, not with the interest rate. That same habit is why we’re now looking at existing apartment buildings of up to 100 units, where the return comes from fixing what’s broken inside. At today’s rates, heavy borrowing works against you, so the gain has to come from running the building better, not from the fee playbook regulators accused the largest Wall Street landlord of running, which I wrote about in May. That suits patient investors who don’t need much debt, like families and family offices (firms that manage the money of one or a few wealthy families). A fix takes months, and a building without a big loan on day one can afford to wait for it. So, on the last rental you looked at: was the return coming from the income you’d buy, or from what you’d fix?
If you’re weighing a building like this, send me a DM on LinkedIn. I’m always glad to compare notes or answer questions.
Until next week,
Luis
Sources
- Freddie Mac — Mortgage Rates Average 7.28% (October 1, 2026) — 30-year fixed 7.28%, prior week 7.03%, a year ago 6.34%.
- Freddie Mac — PMMS weekly history (CSV) — last weekly 30-year reading above 7.28%: 7.29% on November 22, 2023.
- CBRE — U.S. Cap Rate Survey H1 2026 — stabilized and value-add cap rate definitions; greater compression for class B/C and value-add; class C expansion expectations; infill multifamily most bearish subtype.
- NMHC — Who Owns America’s Apartments? Ownership Patterns Across Property Sizes and Markets (Chris Bruen, March 24, 2026) — HUD 2024 RHFS individual-investor ownership by property size; “relatively little empirical research”; 608,000 multifamily deliveries in 2024, 90.1% in 20+ unit buildings, 2.7% in 2–4.
- HUD — HUD and Census Bureau Release Findings of 2021 Rental Housing Finance Survey (November 29, 2022) — professional management: ~22% of 1–4-unit properties, 84% of 150+-unit properties.
- NAHB Eye on Housing — Single-Family Permitting Declines Through July as Multifamily Activity Remains Stronger (September 15, 2026) — Florida multifamily permits −31.2% YTD through July; U.S. multifamily +6.3%.
- NAHB Eye on Housing — Energy Prices Rise Again in August (September 10, 2026) — residential building materials ex-energy +5.1% year over year.
- Prior published in this newsletter: 100% Bonus Depreciation Is Now Permanent (September 29, 2026) · The Fed Raised Rates 12–0 (September 21, 2026) · Family Offices Are Cutting Real Estate Allocations. In the U.S., They Just Doubled Down. (August 4, 2026) · Wall Street Isn’t Raising Your Rent. It’s Keeping You a Renter. (May 4, 2026)