← Lana Development | Projects | Contact

Blog

  • Florida New Construction Is Down 31%. The Builders Who Survived Are Not Who You Think.

    Florida New Construction Is Down 31%. The Builders Who Survived Are Not Who You Think.

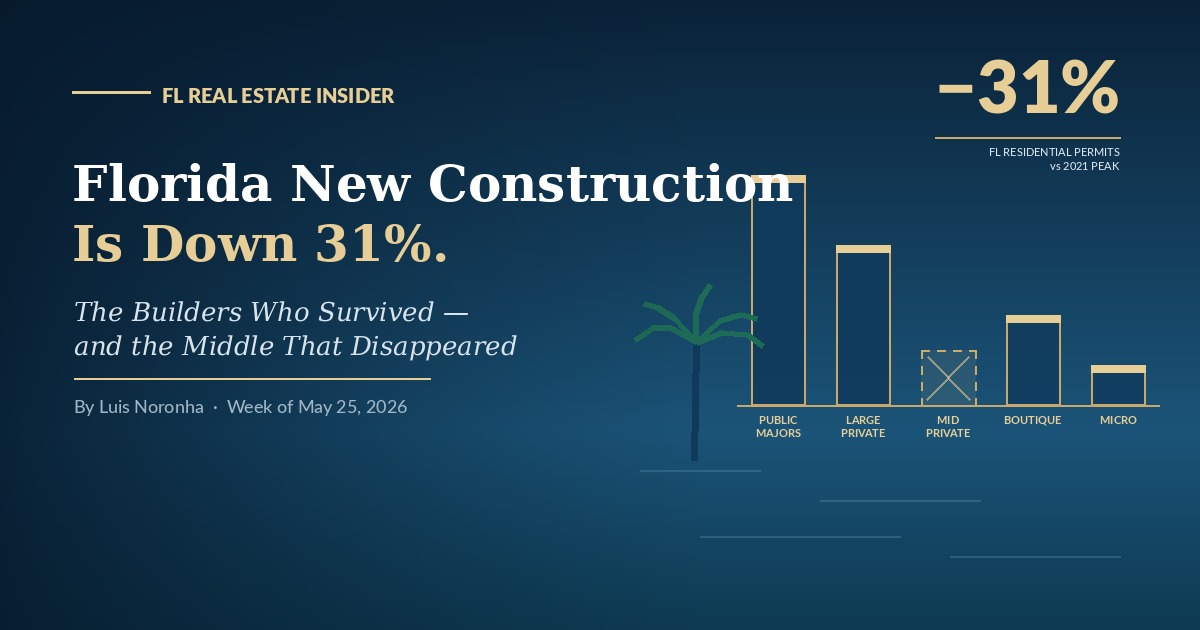
    Florida new construction down 31% — bar chart with hollowed-out mid-market builder tier

    Why the only Florida operators left standing are the very largest publics, the very disciplined privates, and almost no one in between — and what that gap means for capital.

    FL Real Estate Insider — Week of May 25, 2026 By Luis Noronha


    A number that should be on the front page of every Florida real estate publication this spring, and instead is in almost none of them: Florida residential building permits are down roughly 31% from the 2021 peak. (Shovels — Florida Housing Market Outlook: What Building Permit Data Says)

    That is not a normal-cycle slowdown. That is a structural reset of the supply side of the Florida new construction market, and the part of the story that nobody is telling cleanly is who is still building and who is not.

    This week I want to lay out what the permit data actually shows, what the public homebuilders’ first-quarter 2026 earnings actually say about Florida, what is happening to the private builder cohort that used to fill the middle of this market, and — clearly marked as opinion — what I think it means for capital allocated to ground-up Florida new construction over the next 24 months.


    What the Florida new construction volume numbers actually say

    Shovels’ Florida permit dataset shows roughly 66,460 new residential construction permits reviewed in 2025, down from 96,951 in 2023 — a 31% reduction in volume. The cycle low was 2024, when the year-over-year drop hit 21%; 2025 ticked up 1.4%, which is meaningful as a floor signal but is a long way from a recovery. (Shovels — Florida Housing Market Outlook)

    The U.S. Census Bureau’s monthly Building Permits Survey for Florida confirms the directional read in the official federal data and is the place to verify any single-month or single-county number. (U.S. Census Bureau — Building Permits Survey, State Monthly, FRED — New Private Housing Units Authorized by Building Permits for Florida (FLBPPRIV))

    The headline read most coverage settles on is “Florida is overbuilt and needs to absorb.” That is half right. The state did overbuild specific submarkets in 2021–2022 — Southwest Florida especially — and the inventory in those metros is still working off. But the permit number is a forward indicator of supply, not a backward indicator of absorption, and what it is telling you is that the operators who can pull permits at scale in Florida today are a much smaller and much more concentrated group than they were four years ago.


    Who is still building: the publics are eating the market

    Inside Florida, the share concentration at the top is severe. Lennar led Florida permits in early 2026 at roughly 1,111 permits, D.R. Horton at 690, PulteGroup at 379. (HBWeekly — Florida’s Top Home Builders, December 2025 Market Snapshot, HBWeekly — Florida Top Home Builders, January 2026) Nationally, D.R. Horton closed more than 87,000 homes in 2025 — the No. 1 spot it took from Lennar two years earlier. (Builder Magazine — The 5 Home Builders Leading the Nation in Closings)

    That concentration is being held up by an incentive package smaller competitors cannot match. Lennar reported Q1 2026 sales incentives at roughly 14% of sales price, against a historical average of 4% to 6%, and new orders nonetheless grew 1% year-over-year to 18,515 homes. (Lennar — Form 10-Q for the quarter ended February 28, 2026, FinancialContent — Lennar Q1 Earnings Signal Shift in Housing Market) D.R. Horton’s Q1 2026 homebuilding revenue fell 9% to $6.5 billion and pre-tax homebuilding income fell 30% — yet new sales orders were up year-over-year. (D.R. Horton — Q1 FY2026 Earnings Release)

    The mechanism is the captive mortgage subsidiary. DHI Mortgage, Lennar Mortgage, and Pulte Mortgage can deliver below-market rate buydowns — typically 100 to 200 basis points, plus closing-cost credits — on the parent’s own inventory, financed off the parent’s balance sheet. (The Globe and Mail — Homebuilder Earnings: D.R. Horton Sticks Out as Pulte & NVR Sales Tank) A small or mid-sized private builder cannot match that package without taking the project to a loss.


    The land-banking layer that institutionalized the gap

    The second structural advantage is one almost no consumer-facing Florida real estate coverage has connected to homebuyer outcomes: the land-banking spin-off model.

    On February 7, 2025, Lennar completed the taxable spin-off of Millrose Properties, advancing what it has called since 2013 a strategy of becoming a “pure-play land-light manufacturer of homes.” Millrose buys and develops residential land, then sells finished homesites back to Lennar under option contracts with predetermined costs and takedown schedules. It is externally managed by Kennedy Lewis Land and Residential Advisors, an affiliate of Kennedy Lewis Investment Management — an institutional firm with more than $25 billion in assets under management. (Lennar — Lennar Completes Spin-off of Millrose Properties (Feb 7, 2025), SEC — Millrose Properties Form 424B1, FY2025)

    A mid-sized Florida private builder bidding against a Millrose-funded lot takedown is, in effect, bidding against Kennedy Lewis. Industry coverage of the broader sector notes that “you can’t attend an industry conference without encountering multiple new land bank funds.” (HousingWire — Understanding Homebuilding’s New Capital Partner: Land Banking, John Burns Research and Consulting — Land Banking Grows as Housing Industry Strategy)


    The private-builder cohort being squeezed

    The other end of the same trend is now showing up in the bankruptcy docket. The Florida 2025 builder-failure list is not a list of small operators that got over their skis — it is a list of well-known builders with long track records:

    The common factors in the post-mortems are not surprising — insurance during construction roughly doubled across the 2022–2024 cycle, materials cost volatility caught builders working off fixed-price contracts, and labor markets stayed tight — but the structural explanation is the cost-of-capital gap. When the largest publics can self-fund a rate buydown, schedule a finished lot off an institutional land bank, and underwrite a project on volume economics, the private builder running the same project off a regional bank construction loan and a self-financed lot is competing on a different P&L.

    Industry M&A is the next step in the same pattern. New Home Co. completed its acquisition of Landsea Homes Corporation in early 2026, creating a privately-held top-25 national homebuilder — a transaction explicitly framed by both parties as a defensive response to scale-driven cost-of-capital pressure. (Rise Well Homes — New Home Co. Completes Acquisition of Landsea Homes Corporation)


    The lane the publics structurally don’t serve

    Here is the part of the story that matters for the audience this newsletter is actually written for.

    The volume-merchant new-construction model the publics run in Florida — D.R. Horton’s median price tier, Lennar’s median tier, Pulte’s median tier, plus the rate-buydown package — is overwhelmingly aimed at the first-time and first move-up financed buyer below the conforming loan limit. It is built around mortgage origination. It is not built around the buyer profile that is currently driving the Florida price tiers that are not softening.

    That buyer profile is cash. I am going to stay on one county and one tier for all of it, because mixing geographies and price tiers is exactly how this gets overstated — and Miami-Dade is the only Florida county publishing a verifiable cash share at the top of the market:

    • 82% of Miami-Dade $1 million-and-up condo sales closed all-cash in 2025, against a national all-price share of roughly 25%. Four in five transactions in that tier never touch a lender. (MIAMI REALTORS®)
    • Below the luxury tier the county still runs far above the national norm: cash was 38.1% of all Miami-Dade closed sales in June 2026 — 48.5% of existing condo sales and 27.6% of single-family. (MIAMI REALTORS®) Miami-Dade posted a 40% cash share in December 2025 against a 27% national average. (MILLION)
    • And the tier is growing, not shrinking: in the second quarter of 2026, $1 million-plus sales across Miami-Dade, Broward, Palm Beach, the Treasure Coast and Southwest Florida rose 20.1% to 8,013 single-family homes and 23.5% to 2,590 condos. (Keyes/Illustrated Luxury Market Report, Q2 2026, via RISMedia)

    Two honest limits on that. It is one county — no comparable cash share is published for Palm Beach or Southwest Florida, and on volume those markets are larger at the top than Miami-Dade is. And the 82% is a condo figure; no matching number exists for million-dollar single-family. I would rather give you a narrow number that holds than a statewide one that does not.

    The customer in those numbers does not need a 200-basis-point rate buydown. The captive-mortgage advantage that the publics use to dominate the first-time-buyer market is irrelevant to a cash buyer at the top of the market. And the volume-merchant production model the publics run is structurally bad at producing the customized, code-current, primary-residence product that cash cohort actually wants — partly because it does not match their distribution, partly because the margin math on a custom-spec project does not fit a public homebuilder’s quarterly earnings cycle, and partly because the publics have spent the last decade explicitly de-emphasizing the land-heavy custom-spec model in favor of asset-light merchant-build.

    That is the lane.


    What I think — clearly marked as opinion

    I want to clearly mark what follows as my view, not data.

    Read together, the 31% permit decline, the public-builder incentive escalation, the land-banking buildout, and the private-builder failure list are not four separate stories. They are one story: the Florida new-construction supply side is being squeezed into two viable lanes and hollowed out everywhere in between.

    Lane one is the merchant-build volume tier the publics dominate, and they will keep dominating it. Trying to compete with D.R. Horton in 2026–2027 on a 25-home subdivision priced at a first-time-buyer mortgage is, for almost any private builder, a strategic mistake.

    Lane two — the one that matters to a serious capital allocator — is custom-spec, code-current, primary-residence product priced for the cash and HNWI move-up buyer. That lane has three durable advantages right now that I do not believe are temporary:

    First, the end buyer pays cash, so the rate-buydown dynamic that decides the financed tiers does not apply. Lane two competes on product, location, and execution.

    Second, the supply side in lane two has measurably thinned as the small and mid-sized private builders who used to fill it either failed, sold to a larger platform, or moved into project-management work for a public. Less competition for the same end-buyer demand is the most direct definition of pricing power I can give you.

    Third, the structural tailwinds I have flagged in recent issues — the insurance wedge in favor of code-current construction, the GSE underwriting wedge in favor of code-current condos, the property-tax reform conversation that disproportionately rewards homesteaded primary residences — all flow through this exact lane. (Background: The Florida Property Tax Fight, Without the Talking Points, The Condo Cliff, Wall Street Landlords.)

    The counterpoint to my own thesis: this is not a permanent moat. The publics are smart, the institutional land-bank vehicles will eventually reach further up the price tier, and the cash-buyer pool can soften if global liquidity conditions change. The reading I am giving you is a 24-to-36-month view, not a 10-year view. But on that horizon, the structural setup is as favorable as I have seen it in this cycle.


    From the Developer’s Seat

    This section is my view, not data.

    The single sentence I would offer a sophisticated capital allocator looking at Florida new construction right now: the operators left standing in the lane I would want to deploy into are a much smaller, much more identifiable group than they were three years ago — and the structural advantages of being in that group are widening, not narrowing.

    Patient, code-current, custom-spec primary-residence development priced for the HNWI move-up and cash buyer is the lane Lana is built for. It is also the lane in which family-office and HNWI capital — patient, willing to underwrite a 24-month ground-up cycle, earning co-invest economics no institutional REIT can match — has its largest structural edge.

    If you are an accredited investor and want to see how this thesis is expressed in named, live Lana projects with full underwriting transparency, that is what the Lana Investor Memo exists for. Reply to this email and I will add you to the next memo distribution.


    Sources

  • The Florida Property Tax Fight, Without the Talking Points

    What is actually on the table in 2026, what is not, and who would quietly win if any of it reaches the ballot

    FL Real Estate Insider — Week of May 18, 2026 By Luis Noronha


    For the last six months, every Florida real estate conversation I have been in eventually turns to the same question: “is the property tax thing actually happening?” The honest answer is that the political pressure is real, the proposals are real, and the mechanics of who would benefit are very real — but almost none of the public commentary you have read about it is accurate enough to use.

    So this week I want to do something different. I want to lay the actual proposals out side by side, with the bill numbers, what each one would do mechanically, where each one died in this past session, and what each would mean for a Florida property owner depending on whether you live in your house, rent it, or hold it as an investment.

    Then I will mark — clearly — what I think, separate from the statute.


    What is actually on the table

    Florida’s 2026 regular session produced a cluster of House Joint Resolutions aimed at homestead property taxes. They are not interchangeable. Each does something different, each cleared a different point in the process, and each carries a different bet about who benefits.

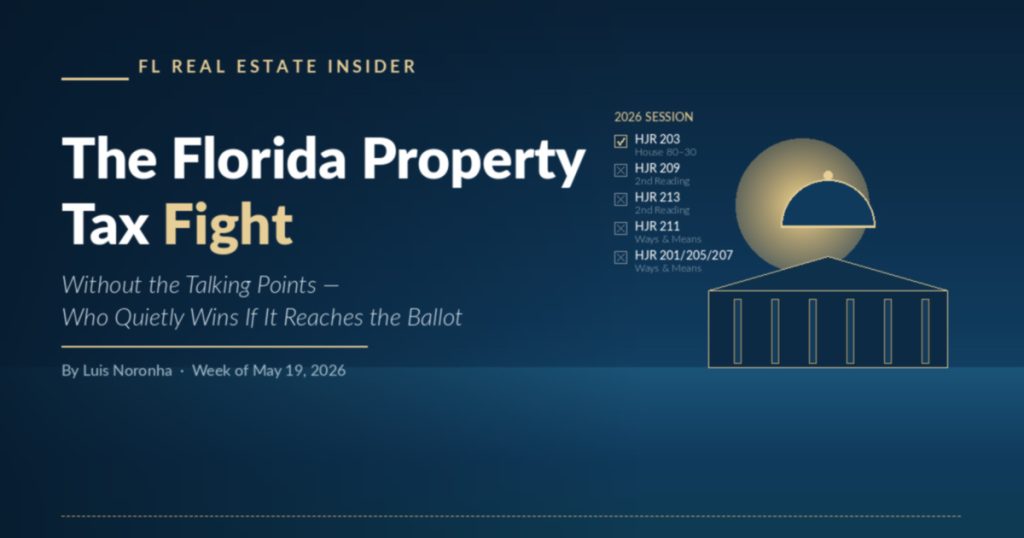
    HJR 203 — phased elimination of non-school property tax on homesteads. Increases the homestead exemption from non-school ad valorem taxes by $100,000 per year for ten years beginning in 2027, until homesteaded primary residences are fully exempt from non-school property tax by 2037. School property taxes are preserved. HJR 203 passed the House 80–30 on February 19, 2026 — the only proposal to receive a floor vote — and then died in the Senate Appropriations Committee when the regular session ended March 13, 2026 without a hearing. (HJR 203 bill page, Florida House, Florida Phoenix coverage, Florida Policy Institute bill summary)

    HJR 209 — a new $200,000 second homestead exemption conditioned on carrying comprehensive property insurance. Stacks on top of the existing homestead exemption, applies only to non-school ad valorem taxes, and applies only to homesteads carrying a comprehensive multiperil policy. The Revenue Estimating Conference put the local-government revenue cost at roughly $8.6 billion per year, and the legislative analysis estimated that about 83 percent of Florida homesteaded homeowners would qualify. HJR 209 cleared all of its committees but died on the Second Reading Calendar without a floor vote. (HJR 209 bill page, Florida House, Florida Policy Institute bill summary)

    HJR 213 — reassess homestead property every three years instead of every year, with the cumulative cap held at 3 percent or CPI. Materially slows assessed-value creep for long-tenured homesteaders. Cleared committees, died on the Second Reading Calendar. (Florida Policy Institute bill summary)

    HJR 211 — remove the $500,000 cap on Save Our Homes portability. Allows a homesteader to transfer the full accumulated SOH benefit to a new primary residence, not just the first $500,000. Stalled before Ways and Means. (Pegasus Lends portability summary, Florida Policy Institute bill summary)

    HJR 201, 205, 207 — additional homestead-exemption increases of varying sizes and structures. All stalled before Ways and Means. (Florida Policy Institute bill summary)

    Net of all of that: the 2026 regular session produced exactly one proposal that made it to a full chamber vote, and the April 2026 special session — which also covered the budget — adjourned without putting any property tax measure on the November 2026 ballot. (WFLX coverage of session end, Barnes Walker post-session update)


    What everyone is now waiting on

    The path forward, if there is one, runs through a third special session this summer. Governor DeSantis has signaled July or August 2026 as the likely window, contingent on a deal with the Senate. To get a constitutional amendment on the November 2026 ballot, both chambers need to approve it with a 60 percent supermajority, and the Secretary of State has a late-August certification deadline. Voters would then need to approve the amendment with a 60 percent supermajority to ratify it. (Fox Business — DeSantis phased approach, WFLX — third special session)

    The Senate is the real story. Senate President Ben Albritton has been explicit that the Senate is not ready to send a property tax amendment to the ballot without first solving for the impact on what he has called Florida’s “fiscally constrained” counties. Senate Appropriations Chair Ed Hooper put it more plainly: “There’s 67 totally different counties in this state, and a property tax issue that is great for one county could crush 31 poor counties.” (Florida Voice — Albritton final message, Florida Realtors — Lawmakers continue work on property tax plan)

    That is the negotiating wall. The House wants to give voters an option in November. The Senate wants to first answer the question “and how do small counties pay for sheriffs and roads?” before it agrees to anything.


    The replacement-revenue math, which is the part nobody on the political side wants to be specific about

    The piece of this that the talking points consistently soft-pedal is what replaces the revenue. Florida’s homestead non-school property tax base is large enough that the only credible single-lever replacement is a substantially higher sales tax. The Florida Policy Institute’s analysis concluded that fully replacing the lost revenue with sales tax would require Florida to roughly double its state sales tax to about 12 percent — which would be the highest state sales tax rate in the country. (Kiplinger summary of FPI analysis)

    Florida TaxWatch has not endorsed elimination either. Brandi Gunder, Florida TaxWatch’s vice president for research, said publicly that “tax levies are growing at an unsustainable pace” but also that any restructure “has to be a partnership between local, state — everybody on board to know how critical government services will be funded.” (WUSF — TaxWatch on property tax elimination)

    Translation: even the conservative-leaning fiscal watchdog is not going to wave this through without a credible replacement plan.


    What the live bills would actually do, for the actual people who own actual property

    This is where most of the public commentary breaks down. Let me put the mechanics in plain English.

    If you own and live in your home (homesteaded primary residence): every live proposal benefits you, on different timelines. HJR 209 would deliver the biggest immediate cut on day one — a $200,000 additional exemption stacked on the existing $50,722 baseline exemption (propertyexemption.com — Save Our Homes 2026 guide), conditional on carrying comprehensive insurance, for a total exemption around $250,722 on non-school taxes. HJR 203 would deliver a deeper cut but over a decade. HJR 213 would slow your assessed value growth. HJR 211 would let you carry your full SOH benefit to your next primary residence with no $500,000 cap.

    If you own a second home, an investment property, an Airbnb, or commercial property: none of the live proposals reduce your property tax. The phased elimination in HJR 203 specifically excludes non-homestead property; HJR 209 explicitly excludes non-homestead property; the SOH-related proposals are structurally tied to homestead status. The existing 10 percent non-homestead assessment cap (Florida Statute 193.1556) continues to apply, with the standard reset to full market value upon ownership change. (Pinellas County PA — Non-Homestead 10% Cap)

    If you rent in Florida: none of these proposals delivers you direct relief, and the replacement math is structurally regressive — sales tax falls more heavily on lower-income households as a share of income than property tax does. (Kiplinger summary of FPI analysis)

    If you are about to close on a new construction primary residence: this is the corner of the market that gets the least public attention and where the mechanics are most interesting. Under existing law, new construction is reassessed at full market value as of the first January 1 after substantial completion, and is added to the capped assessed value of the land. Once homestead is filed, the 3 percent (or CPI) Save Our Homes cap kicks in for the following year. (Florida Department of Revenue — Property Tax Information for First-Time Florida Homebuyers (PDF), § 193.155, Florida Statutes) Layering HJR 209 or HJR 203 on top of that mechanic would compress non-school property tax on a new code-current primary residence faster than on essentially any other asset class in the state.


    What I think — clearly marked as opinion

    I want to clearly mark what follows as my view, not statute.

    The political framing of this debate has been “homeowners versus government,” and that framing is making people miss the more important story. Every live proposal that came out of the 2026 session — HJR 203, HJR 209, HJR 213, HJR 211, all of them — concentrates the benefit on owner-occupied primary residences. By design. Some of them go further and condition the benefit on the property carrying insurance that an actual carrier is willing to write, which in Florida in 2026 means a structure built to current code is materially advantaged over older, harder-to-insure stock.

    If any version of this package reaches the November 2026 ballot and passes, three things follow.

    First, the relative carrying cost of a homesteaded primary residence drops, and drops most for higher-assessed-value homes — which is the segment with the largest absolute non-school millage bill. That is a transfer toward the move-up and luxury primary-residence buyer, which is the segment new code-current construction is built for.

    Second, the relative carrying cost of investor-held inventory — second homes, short-term rentals, institutional single-family-rental portfolios — does not drop. The owner-occupied buyer is being explicitly advantaged versus the investor buyer at the margin. That is a small but real tailwind for end-buyer-driven new construction and a small but real headwind for institutional SFR exposure in Florida — which builds on the pattern I have written about in prior issues. (FL Real Estate Insider — Wall Street Landlords)

    Third, the insurance-conditioned design of HJR 209 specifically rewards buildings that current Florida carriers are willing to write — which means, in practice, FBC-current construction. The reform package and the insurance market are quietly pointing at the same asset.

    I am not predicting any of these proposals passes. The Senate roadblock is real, the replacement-revenue problem is unsolved, and the political appetite for raising sales tax to 12 percent does not exist. The most likely outcome remains a partial package — most plausibly some form of HJR 209 (insured-homestead exemption) plus an expanded portability fix — rather than full HJR 203 elimination.

    But the part of this that will happen, whatever the November ballot ends up looking like, is that the political conversation is now permanently anchored on giving more of the tax relief to owner-occupied primary residences. That anchor is not moving. And whoever is positioned to sell or hold owner-occupied primary residences in Florida is on the right side of that anchor.


    From the Developer’s Seat

    This section is my view, not statute.

    I read the entire 2026 property tax package as a slow tilt of the rules toward exactly one buyer profile: the homesteaded, well-insured, primary-residence owner of a code-current Florida home. Every live proposal advantages that buyer. The 10 percent non-homestead cap (and the reassessment-on-sale mechanic) keeps the rules less favorable for investor-held and second-home inventory. The insurance condition in HJR 209 quietly favors structures that today’s carriers will write — which means structures built to current FBC. None of this is accidental.

    The practical implication for capital is straightforward. The Florida residential lane with the most political wind at its back is owner-occupied, code-current, primary-residence new construction priced for an HNWI move-up buyer. That is the lane Lana operates in. It is also the lane in which family-office and HNWI capital has a structural advantage over institutional capital, because the holding period, the buyer profile, and the underwriting risk are all things patient private capital handles better than a public REIT or a Wall Street SFR vehicle. If you are an accredited investor and want to see how this thesis is actually expressed in live projects with named underwriting, that is what the Lana Investor Memo is for. Reply to this email and I will add you to the next memo distribution.


    Sources

  • The Condo Cliff, Two Weeks Later: New Data, Same Direction — and a Financing Change Almost Nobody Is Talking About

    The Condo Cliff, Two Weeks Later: New Data, Same Direction — and a Financing Change Almost Nobody Is Talking About

    Florida condo cliff — older oceanfront tower on the edge of the SB-4D financing shift

    New data, same direction — and a financing change in August that almost nobody is talking about

    FL Real Estate Insider — Week of May 11, 2026 By Luis Noronha


    Two weeks ago I wrote that Florida’s older-condo market is at the front of this story, not the back of it — that the reform is right, the transition is being managed thinly, and the market has not yet priced what’s coming. Several readers wrote back asking the same thing in different words: fine, but show me the numbers.

    Fair. So let’s look at what’s actually moved in the last few weeks. Nothing in the data changes the thesis. If anything, it sharpens it.


    The inventory picture

    The clearest signal is supply, and the cleanest way to see it is condo inventory measured against single-family in the same state in the same month. Statewide, Florida condo and townhouse inventory stands at an 8.1-month supply against 4.5 months for single-family — nearly double. (Florida Realtors) In Southeast Florida the gap is wider and the forecast says it persists: the MIAMI REALTORS® outlook has condo months’ supply at 12.9 at the end of 2025, easing only to 11.6 by the end of 2026 and 9.6 by the end of 2027, while single-family tightens from 5.7 to 4.9 to 4.2. (MILLION) Those are levels that in any normal market would be flashing red — and they are forecast to stay elevated through 2027.

    Inside that headline, the inventory is not evenly distributed. Newer-build condos are still trading on relatively normal timelines. The supply pileup is concentrated in older coastal buildings — exactly the cohort caught in the post-SB-4D capital cycle, and exactly the cohort I described two weeks ago. (NBC 6 South Florida — surge in condo listings)

    This is what “we are at the front of this story” looks like in data. Supply is building. Pricing in the older segment hasn’t yet fully adjusted to it, because most sellers are still anchored to 2022–2023 comps. That gap — between supply reality and seller expectation — is where the opportunity sits.


    What the assessments actually look like (without making numbers up)

    I refused to quote an “average” assessment last issue, because there isn’t one. There still isn’t. But there is now enough public reporting to talk about ranges responsibly.

    Reporting across covered buildings, particularly 1975–1995 mid- and high-rise towers, shows special assessments commonly in the $30,000 to $75,000 per unit range, with combined roof, concrete restoration, and waterproofing programs producing assessments above $100,000 per unit in the most exposed buildings. Some industry coverage cites a broader observed range of $5,000 to $150,000 per unit, which is consistent with the variance you’d expect across age, reserve discipline, and structural condition. (Florida Realty Marketplace — 2025 Condo Bill, MishTalk — Florida Condo Owners Dump Units)

    The scale of the population affected matters more than any single number: roughly 900,000 Florida condo units sit in buildings 30+ years old and are inside the regulatory perimeter. That is the cohort the market is going to have to digest over the next 24 months. (Aerially — SB-4D Complete Guide)


    The financing change in August that almost nobody is pricing in

    Here is the development that has moved most since the last issue, and that almost none of the residential agents I’ve spoken to are talking about yet.

    Effective August 3, 2026, Fannie Mae is eliminating Limited Review for condominium loans. Every condo loan in a project with more than ten units will require a Full Review. The lender-delegated Full Review covers reserves (with Fannie’s minimum reserve allocation rising from 10% to 15% for loan applications dated on or after January 4, 2027), insurance adequacy, deferred maintenance, special assessments, and litigation — the exact items SB-4D is forcing out into the open in older Florida buildings. (Fannie Mae — Lender Letter LL-2026-03, CommunityPay — Fannie Mae Eliminates Limited Review, BCP Mortgage — Fannie Mae 2026 Condo Guidelines)

    Translation, in plain English: starting in August, the conforming financing path for an older Florida condo runs straight through the same documentation that SB-4D is generating. A building with an incomplete milestone inspection, an unfunded SIRS, or an active uncalled assessment is going to look different to an underwriter on August 3 than it did on August 2.

    For context on where the universe currently sits: as of last summer, only about 3.6% of condo projects nationally were flagged “ineligible” in Fannie Mae’s Condo Project Manager system. The top two reasons: insufficient master insurance and critical repair issues, including failure to meet state or local inspection requirements. With the policy change, the practical bar for a condo loan goes up across the board — and disproportionately in Florida. (Fannie Mae — Ineligible Projects, KSN Law — Fannie Mae Unavailable List)

    There is one favorable counter-development worth naming. As of March 18, 2026, Fannie Mae retired the Florida-specific PERS pre-review step for new or newly-converted attached condo projects, putting Florida new construction back on the same lender-delegated Full Review footing as the rest of the country. That helps new-build supply. It does nothing for the 30-year-old tower with a pending assessment. (Fannie Mae Condo Project Manager FAQs (March 2026))

    The bifurcation between buildings that can be conventionally financed and buildings that effectively cannot is about to get sharper. And it will start showing up in price before the year is out.


    The opportunity I flagged last time, with the timing window now visible

    This is the part where I owe readers more than I gave them in the last issue.

    The case I made was that for the prepared cash buyer or experienced operator, the post-SIRS environment creates real opportunity in older buildings — provided you underwrite the building, not the unit. That is still true. What’s clearer now is the window.

    The final SIRS deadline is December 31, 2026 — about seven months from today. Most older buildings were due by December 31, 2025, but an association whose milestone inspection is due by the end of 2026 may finish both together, and no SIRS may be completed after December 31, 2026. (Fla. Stat. § 718.112(2)(g)) Between now and then, three things are happening simultaneously:

    1. More SIRS reports are being issued, meaning more buildings move from “unknown” to “documented” — and documented is generally better for a serious buyer than unknown. 2. Inventory is continuing to build in older coastal stock, putting downward pressure on prices in buildings that have not yet completed their cycle. 3. The August Fannie Mae change is going to thin the financed-buyer pool in many of these same buildings, leaving cash buyers and portfolio lenders with less competition. (Here’s how that call held up.)

    Read those three together. The next two to three quarters are the period where a disciplined buyer, willing to do the underwriting work, has the most leverage. After the SIRS deadline passes and the dust settles, the better-managed older buildings will reprice upward as the uncertainty discount comes out. The badly-managed ones will keep drifting.

    The market still has not priced this. It is starting to.


    What I’d tell different people today

    These are the same audiences I addressed two weeks ago. The advice is the same; the urgency is higher.

    If you own in a covered building: Get the SIRS, the milestone inspection, and the current reserve balance, and look at them honestly. If your building is still vague on timing, the August Fannie Mae change is a strong reason to push your board for clarity now. A building that closes 2026 code documented compliance and a credible capital plan is going to trade meaningfully differently than a building that doesn’t.

    If you serve on a board: Communicate. The owners who feel ambushed are the ones who flood the market with simultaneous listings and crater building values for everyone. The boards getting the best outcomes right now are the ones running the most transparent processes — not the ones trying to spin them.

    If you’re a buyer with cash or portfolio financing: This is the underwriting window. Look for buildings that have done the work, priced the work, and started executing — and where seller expectations haven’t yet caught up to the SIRS disclosure. Get the documents before you make an offer, not after. Underwrite the building. Then underwrite the unit.

    If you’re a legislator: A bridge financing or deferred-payment mechanism for long-tenured owners hit by six-figure assessments would still be the right move. We are not running out of time to do this. We are running out of political room to do it cleanly. The Aug 3 Fannie Mae change is going to make the affordability cliff more visible in real time. Please act.


    Bottom line

    Nothing in the data of the last two weeks contradicts what I wrote two weeks ago. The market still hasn’t priced this. The opportunity is still real for the prepared. The window is starting to narrow.

    If you read the last issue and forwarded it to one person, this is the one to forward to a second.

    — Luis


    From the Developer’s Seat

    Several readers wrote back after the last issue with a version of the same question: if the older-condo segment is this dislocated, why aren’t you — a Florida developer — building in it?

    I want to mark what follows as my view from the developer’s seat, not market reporting.

    The economics of ground-up, code-current new construction, in product types where the end buyer is HNWI rather than rate-sensitive, run in the opposite direction of what’s hitting older condos. New product is built to current Florida Building Code and prices accordingly on insurance. It doesn’t trip the Fannie Mae review screens described above, because the deferred maintenance, the unfunded SIRS, and the milestone-inspection backlog simply don’t exist on day one. And in my experience underwriting buyers for new luxury and move-up Florida product, the end buyer is materially less interest-rate-sensitive than the cohort being forced out of impaired older towers.

    The dislocation in the resale-condo segment isn’t a headwind for the new-construction-for-HNWI lane. It’s a tailwind. Capital displaced from impaired older stock has to land somewhere, and well-positioned new product is one of the few places left where it can.

    That is the lane Lana Development builds in — Galleria Villages, Turquoise Homes, Waterview, West Bay. If you’re a HNWI or family-office investor evaluating where Florida residential capital actually has an edge in 2026, reply with “Investor Memo” and I’ll add you to a separate, accredited-only track I’m setting up alongside this newsletter.


    FL Real Estate Insider exists to cover the parts of Florida real estate that get glossed over in the brokerage marketing emails. If this helped, hit reply with the building you’re worried about — I’m happy to point you to a qualified attorney, structural engineer, or broker. No pitch attached.


    Sources

  • Wall Street Isn’t Raising Your Rent. It’s Keeping You a Renter.

    117,000 Florida homes, a 35% share of eviction filings, and a $48 million FTC settlement — what the institutional partition of Florida single-family actually means

    FL Real Estate Insider — May 2026 Issue
    By Luis Noronha


    Drive through almost any new-built subdivision between Lakeland and DeLand and play a game: count the houses with the same beige paint, the same xeriscaped yard, the same blank-eyed front door. The ones where you can’t quite tell who lives there. Pull up the property appraiser. Most of those deeds don’t have a person on them. They have an LLC with a name like SWAY 2014 BORROWER LLC or JEFF 1 LLC — and that LLC rolls up to one of a handful of companies headquartered nowhere near Florida. (Tampa Bay Times — Buying up the Bay)

    The story that institutional landlords are jacking up your rent is the easy one to tell. The Florida data tells a different one — and it’s a bigger problem for the Florida that homeowners thought they were buying into.


    117,000 Florida homes — and who actually owns them

    The Tampa Bay Times’ year-long Buying up the Bay investigation, the first state-level analysis of its kind, found that corporate real estate investors now own more than 117,000 single-family homes across Florida. (Tampa Bay Times, Florida Trend)

    The concentration is sharper at the metro level than the statewide number suggests:

    • In Pinellas and Hillsborough counties combined, the top 10 corporate investors control roughly one in five single-family rentals. (Tampa Bay Times)
    • The five largest corporate landlords in the Tampa Bay region together own about 20,000 single-family homes. (Tampa Bay Times)
    • The Government Accountability Office’s March 2026 report puts institutional ownership at 15% of the Tampa metro single-family rental market, and an Urban Institute analysis found Tampa with roughly 23,000 institutional-owned homes. (GAO-26-108675, Urban Institute)
    • Jacksonville is the most concentrated metro in Florida — 21–22% of single-family rentals owned by institutional investors per the GAO; the Urban Institute’s earlier estimate ran higher, at 24.2%. (GAO-26-108675, Urban Institute)

    If you operate in any of those metros, the often-quoted “institutional investors only own 2% of US rentals” talking point is irrelevant. (GAO-24-106643) The local concentration is what matters, not the national average.


    What the data actually says about rents

    The conventional populist line is that corporate landlords are coordinating rent hikes and pricing Floridians out of housing. The available evidence does not support that framing as cleanly as it gets repeated.

    What the Tampa Bay Times found, after analyzing tax-parcel records, eviction dockets, and tenant interviews across the region, was that the outsized impact of a handful of companies “can squeeze individual buyers out of the housing market.” (Tampa Bay Times) Not push rents up — push buyers out. That is a different problem, and a more durable one. Every Tampa Bay home that converts from owner-occupied to corporate-rental is a home that will not return to the homeowner inventory in the foreseeable future. Multiply that by 117,000 statewide.

    The University of Florida Shimberg Center’s 2025 Rental Market Study puts the human cost in plain numbers: roughly 905,000 low-income Florida renter households are now cost-burdened, paying more than 40% of their income toward rent. (Shimberg Center) That is the audience that will not be buying in 2026, 2027, or 2028 — and the corporate-rental conversion is one reason why.


    Where the eviction story lives

    If there is a single statistic that should change how Florida thinks about institutional landlords, it is this one. The Tampa Bay Times tracked 2023 eviction filings in Pinellas and Hillsborough by the 10 largest corporate landlords in the region and found those companies accounted for 35% of all single-family rental eviction filings — nearly double their share of the rental homes. (Tampa Bay Times)

    That is not a marginal effect. Invitation Homes alone filed at least 250 eviction cases in Hillsborough County in 2023. (Tampa Bay Times) Princeton’s Eviction Lab, cited in the same reporting, found that large landlords nationally are two to three times more likely to evict than small landlords. (Tampa Bay Times)

    The institutional model relies on rapid eviction-and-re-lease as the response to delinquency. That is a design choice, and it is the mechanism that converts a housing shortage into a churn business.


    The FTC settlement that confirmed the playbook

    In September 2024 the Federal Trade Commission sued Invitation Homes — by far the largest single-family landlord operating in Florida — for a long list of alleged unfair and deceptive practices. The case settled for $48 million. The FTC’s allegations are worth reading in their own right:

    • Advertised monthly rental rates that excluded mandatory junk fees totaling more than $1,700 per year per household.
    • Promised “pre-inspected” homes and “24/7 emergency maintenance” while new residents reported sewage backups, broken appliances, and visible rodent feces.
    • Withheld security deposit funds for normal wear-and-tear and pre-existing damage; pursued eviction proceedings against tenants who had already moved out.

    (Federal Trade Commission, September 24, 2024)

    The FTC began mailing $47.2 million in refund checks to harmed consumers in March 2026. (Federal Trade Commission)

    The point is not that every institutional landlord operates this way. The point is that the largest one in Florida, by the federal regulator’s own findings, did — and the practices the FTC documented are exactly the practices that turn the corporate-rental model into the homeownership-displacement story above.


    What the partition means — and what it doesn’t

    Here is where I think most of the commentary on this goes wrong, in both directions.

    The funds did not buy Florida. They bought a very specific slice of it. Institutional buy-boxes are tight and public: typically 1,500–2,200 square feet, three-bed/two-bath, post-2000 construction, in the same handful of ZIP codes across the I-4 corridor and Duval County. They do not touch 1970s ranches, flag lots, septic, or anything that needs a decision a spreadsheet can’t make. And they are almost entirely absent from the price tiers where the end buyer pays cash.

    So the partition is real, and it is narrow. In the metros and product types the funds targeted, they are dominant — and where they are dominant, the homeownership rate falls and the renter share rises. That is the real cost. Not a few extra dollars on rent, but a generation of Floridians who got priced out of the deed and into the lease, paying junk fees on a home they will never own.


    What this means for our lane

    I want to mark what follows as my view, not reporting.

    Three things follow from the partition, and none of them is “go compete with Invitation Homes.”

    First, the regulatory wind is turning against investor-held inventory, not toward it. Every live property tax proposal that came out of the 2026 Florida session concentrates its benefit on homesteaded, owner-occupied primary residences and explicitly excludes second homes, short-term rentals, and institutional single-family-rental portfolios. The 10% non-homestead assessment cap keeps the rules less favorable for investor-held stock, with a reset to full market value on transfer. The eviction data and the FTC settlement are exactly the kind of record that makes that political anchor harder to move, not easier. Whoever is positioned to sell to an owner-occupier in Florida is on the right side of that.

    Second, the institutional bid and the HNWI move-up buyer are not competing for the same house. A fund underwriting a 1,800-square-foot merchant-build rental at an algorithmic price ceiling is not bidding against a cash buyer choosing a code-current primary residence in a coastal corridor. That matters for basis: the segment of Florida single-family that has an institutional floor under it is not the segment ground-up new construction for the HNWI end buyer is delivering into. The two markets look adjacent on a MLS map and behave nothing alike.

    Third, the displacement has to land somewhere. A generation being pushed out of the entry-level deed does not create demand for luxury new construction — I want to be honest about that rather than pretend the connection is direct. What it does create is a Florida where the owner-occupied primary residence becomes politically and fiscally privileged, where the entry tier is increasingly a rental product owned by someone else, and where the durable homeownership demand concentrates at the tiers that can still clear without financing. That is a slow, structural sort — and it runs in the same direction as everything else I have written about this year.


    What to watch

    The Tampa Bay Times also documented a separate Florida-specific problem in late 2024: a state law that has allowed corporate buyers to terminate condo associations and force out individual unit owners through bulk-purchase mechanisms. (Tampa Bay Times) Expect this to be a 2027 legislative fight, and note where it points: at the same aging condo stock already under SIRS and milestone pressure.

    The FTC settlement is also unlikely to be the last federal action. Single-family rental operators are now an active enforcement target across multiple agencies.


    From the Developer’s Seat

    This section is my view, not data.

    I get asked periodically why Lana does not run a Florida single-family rental strategy, given how much attention the segment gets. The honest answer is that the institutional partition is precisely the argument against it. In the metros where the buy-box is dense, we would be bidding against balance sheets that can pay an algorithmic ceiling and hold indefinitely. In the metros where it is thin, the yield is thin for the same reasons the funds skipped it. Neither is an edge.

    The edge is on the other side of the partition entirely: code-current, developer-led, ground-up product sold to an owner-occupier who pays cash — a buyer the funds do not compete for, in a tenure category the state’s own tax policy is actively privileging, at a price tier where the rate environment is a footnote rather than a gate. Every structural force in this issue points at that buyer: the political tilt toward homestead, the regulatory heat on institutional rental, the hollowing of the entry-level deed.

    That is the lane Lana Development builds in — Galleria Villages, Turquoise Homes, Waterview, West Bay. It is also the lane in which patient family-office and HNWI capital has a structural advantage over institutional capital, because the holding period, the buyer profile, and the underwriting risk are all things private capital handles better than a public vehicle answering to a quarterly cycle.

    If you are an accredited investor and want to see how that shows up in live underwriting — the actual end-buyer profile, the actual basis, the actual corridors — that is exactly the conversation the Lana Investor Memo is built for.

    → Request access at coastal-living-collection.com (accredited investors only).

    — Luis


    FL Real Estate Insider exists to cover the parts of Florida real estate that get glossed over in the brokerage marketing emails. If this helped, forward it to someone who needs to read it.


    Sources

  • The Condo Cliff: Florida’s Post-Surfside Reform Was Right. The Implementation Is Breaking Owners.

    Florida’s Post-Surfside Reform Was Right. The Implementation Is Breaking Owners.

    FL Real Estate Insider
    By Luis Noronha


    On June 24, 2021, at roughly 1:22 a.m., Champlain Towers South — a 12-story beachfront condominium in Surfside, Florida — partially collapsed. Ninety-eight people died.

    The forensic record is now public. Long-term concrete degradation in the basement-level parking garage and pool deck, water penetration, corrosion of reinforcing steel. Structural concerns had been documented as far back as 2018 and described as “much worse” in April 2021. A roughly $15 million remediation program had been approved by the association before the collapse — but the main structural work hadn’t started.

    Four years later, the legislative response to that night is reshaping Florida’s older condominium market in ways most owners are only beginning to feel. The reforms were necessary. The transition is painful. And it’s worth being honest about both.


    What the law actually requires

    Florida’s response came in two pieces of legislation: SB 4-D in 2022 and SB 154 in 2023, which together rewrote Chapter 718 of the Florida Statutes (the Condominium Act) on three fronts. The framework applies to residential condominium and cooperative buildings three stories or more in height.

    1. Milestone Inspections. Every covered building must undergo a milestone structural inspection by December 31 of the year it reaches 30 years of age (measured from the certificate of occupancy), and every 10 years after that. Buildings that had already passed 30 years before July 1, 2022 were required to complete their initial inspection by December 31, 2024. Phase 1 is a visual structural inspection by a licensed architect or engineer; Phase 2 follows if Phase 1 identifies substantial structural deterioration.

    2. Structural Integrity Reserve Studies (SIRS). Associations must commission a SIRS that identifies key structural and waterproofing components, estimates remaining useful life and replacement cost, and provides a funding schedule. Under Fla. Stat. § 718.112(2)(g), existing associations must complete the SIRS by December 31, 2025. An association whose milestone inspection is due on or before December 31, 2026 may complete the two simultaneously, but no SIRS may be completed after December 31, 2026.

    3. Mandatory reserve funding. This is the one with the largest financial impact. For budgets adopted on or after December 31, 2024, funding of SIRS reserves can no longer be waived or reduced by a unit-owner vote. Florida boards had legally been able to underfund or skip these reserves for decades, keeping monthly fees lower than the actual cost of building maintenance. That option is now closed for SIRS components. (A narrow temporary waiver of up to two years exists while repairs are actively being completed, requires a full membership vote, and cannot extend beyond 2028.)

    The statutory home for all of this is § 718.112, Florida Statutes, with the milestone inspection framework primarily in § 553.899.


    Why this hits older buildings hardest

    The economic logic isn’t complicated. For decades, a meaningful number of Florida condo associations — particularly in older coastal buildings — adopted budgets that did not fully fund reserves for major structural components. Members voted year after year to waive or reduce them. That kept monthly fees artificially low and made it easier to sell units, but it deferred maintenance bills onto a future the association did not budget for.

    The law has now ended that deferral. The bills are coming due in two forms simultaneously:

    • Higher recurring fees — because reserves now have to be fully funded going forward.
    • Special assessments — because the SIRS will, in many older buildings, identify substantial work that should have been funded years ago.

    Specific dollar figures will vary enormously by building, age, location, structural condition, and prior reserve discipline. Anyone quoting you a single “average” number is guessing. What is documented is the direction: in buildings that deferred maintenance for decades, the catch-up is real, and it is being paid by current owners.


    The unintended consequence (this is opinion)

    I want to clearly mark what follows as my view, not statute.

    A meaningful share of older Florida condo units — especially in coastal, lower-rise buildings — are owned by long-time residents who paid off their mortgages years or decades ago. These owners are often equity-rich and cash-poor: they own a home outright but live on fixed incomes, may not qualify for new financing against an aging structure, and don’t have the runway to wait out a multi-year capital program.

    When the assessment letter arrives, some of them can absorb it. Many can’t. Those who can’t are facing a forced choice between a loan they can’t get, a HELOC the bank may not write, or a sale at whatever price the market will currently pay for a building that just publicly disclosed major structural work.

    I’ll say plainly what I think is happening: a wealth transfer is taking place, from older long-tenured owners who deferred reserves under rules the state previously allowed, to cash buyers and entities equipped to underwrite the post-SIRS economics. I don’t think anyone designed this outcome. I think it is the predictable consequence of letting reserve waivers run for forty years and then ending them all at once.

    The legislative response was right. The transition is being managed thinly. Both can be true.


    What I’d tell different people right now

    These are recommendations from a developer’s perspective. None of this is legal, financial, or tax advice — get qualified professionals before you act.

    If you own in a covered building: Read the milestone inspection report and SIRS in full. Don’t accept a one-page summary. Push your board for the longest legally permissible timeline on capital projects and assessments. If you are considering selling, understand that disclosure obligations grow as reports are issued — selling earlier in the process is materially different from selling later. And get a real estate attorney before you sign anything, particularly if a buyer is offering a fast, all-cash close on a building that just received its SIRS.

    If you serve on a board: The personal liability exposure for boards under the new framework is real. Document everything. Get the inspection and SIRS done by qualified, licensed professionals — not the cheapest bidder. Communicate openly with owners; the worst outcomes I’ve seen so far have come from boards that tried to soften the message and lost their owners’ trust in the process.

    If you’re a buyer with cash: Older buildings are not all equal. A well-managed building that has already completed its milestone inspection and SIRS, has a credible capital plan, and has begun executing it is a fundamentally different asset than a building still in the disclosure pipeline. Underwrite the building, not the unit.

    If you’re a legislator: The reform is sound. The transition deserves more attention. Bridge financing, deferred-payment programs tied to age and income, or property tax mechanisms that smooth the assessment burden over time would honor the safety intent of the law without disproportionately punishing the cohort least able to absorb the cost. We have time to do this. We are choosing not to.


    What’s coming next

    The reform is now in active execution. Initial milestone inspections for the oldest buildings were due by December 31, 2024. SIRS work was due across covered buildings by December 31, 2025, with an outer limit of December 31, 2026 for buildings completing it alongside a milestone inspection. The reserve funding rules apply to budgets adopted on or after December 31, 2024 — meaning fiscal year 2026 is the first full cycle in which most associations are operating under the new regime.

    Translation: we are at the front of this story, not the back of it. More inspection reports, more reserve studies, more budget letters, and more assessment notices are coming over the next 18 to 24 months.

    If you or someone you care about owns in an older Florida condo and your board is being vague about milestone or SIRS timing, that vagueness is the story. Get the documents. Read them carefully. Get advice from people who are paid to be on your side.


    This newsletter exists to cover the parts of Florida real estate that get glossed over in the brokerage marketing emails. If this was useful, forward it to someone who needs to read it.

    — Luis


    P.S. If you’re trying to navigate a milestone inspection, a SIRS, or a special assessment and you’re not sure where to start, hit reply. I’m happy to point you to a qualified attorney, structural engineer, or broker. No pitch attached.


    Sources

  • Why U.S. Real Estate Investment Remains a Smart Choice in 2026 — And Where the Structural Shift Is Real

    For accredited investors, family offices, and international allocators evaluating U.S. real estate investment in 2026, the fundamental question is not whether the asset class is attractive — the data settles that. The real question is where in the U.S. to be, what product to hold, and how to structure the exposure. This article walks through the macro case for U.S. real estate, and then focuses on where the structural shift is most acute and most durable: South Florida coastal.

    The macro case for U.S. real estate investment

    The United States remains the deepest, most transparent, and best-protected real estate market in the world. The Federal Housing Finance Agency’s House Price Index shows steady long-term appreciation across cycles. Property-title systems give both domestic and foreign buyers legally enforceable rights that most global markets simply cannot match. Foreign ownership faces almost no restrictions — a rarity globally.

    Population dynamics are equally supportive. According to the U.S. Census Bureau and IRS Statistics of Income migration data, between 2020 and 2025 net domestic migration to the Sunbelt exceeded 4 million people, with a disproportionately high-income skew. This is not a speculative wave. It is permanent household relocation driven by tax policy, cost-of-living arbitrage, and lifestyle preference.

    But “U.S. real estate is a good investment” is too broad to be actionable. Within the U.S., the outperformance is heavily concentrated. Let’s talk about where and why.

    Florida: the clearest structural shift in U.S. real estate investment

    Florida added more than 1.9 million residents between 2020 and 2025 — the equivalent of adding a city the size of Philadelphia. According to IRS SOI migration data, the average adjusted gross income of movers from New York exceeded $120,000; from Connecticut, $130,000. Florida has now absorbed more than $36 billion in annual adjusted gross income inflow.

    Three drivers make this durable:

    1. The tax advantage is constitutional. Florida requires a legislative supermajority to impose a state income tax. There is no serious political movement to change it. For a household earning $1M annually, the move from New York to Florida is worth roughly $90,000–$110,000 per year in preserved wealth.
    2. Supply cannot keep up. Coastal land is finite. Buildable footprint in Miami-Dade, Broward, and Palm Beach is constrained by ocean, wetlands, conservation areas, and post-Surfside code updates. Permitting runs 8–18 months in most premium submarkets.
    3. Construction costs are up 35–40% since 2020. According to the CoreLogic Construction Cost Index and BLS JOLTS data, labor shortages and material inflation have raised the barrier to new supply significantly — which structurally protects developers who can build at cost.

    Where investors get U.S. real estate investment wrong

    The most common mistake we see accredited investors make is treating “Florida real estate” as a monolith. Central Florida buy-and-flip strategies, Orlando short-term-rental plays, and Miami condo pre-construction each carry very different risk profiles. The strongest fundamentals concentrate in a specific set of coastal submarkets — Brickell and downtown Miami, Fort Lauderdale/Victoria Park corridor, Boca Raton and Deerfield Beach, and select 30A locations — where lifestyle demand, physical supply constraints, and buyer demographics converge.

    At Lana Development, our Coastal Living Collection portfolio strategy targets exactly this convergence: new-construction luxury residential in Florida’s most resilient coastal corridors, with cycles short enough to compound returns and exits structured at delivery rather than through long-term hold.

    The developer question that matters more than the market question

    Once you’ve decided where to be, the second question — who’s building your investment — matters just as much. According to research from the McKinsey Global Institute (“Reinventing Construction”), the average large construction project runs 16% over budget and 20% over schedule. That gap comes directly out of investor returns.

    A developer who outsources construction to a third-party general contractor absorbs a 15–20% GC markup, is exposed to change-order inflation, and has limited real-time visibility into the project. A developer who is itself a licensed general contractor eliminates the markup, controls the timeline, and can course-correct in weeks instead of quarters. On a $12M build, the difference can exceed $3M in preserved value — every dollar of which flows to the project’s return profile.

    This is the single most important structural question an accredited investor should ask about any real estate opportunity, and it is the reason Lana operates as both developer and licensed GC.

    Investment structures every accredited investor should understand

    Once you’ve settled on market and sponsor, the vehicle matters. Broadly, an accredited investor has four choices:

    • Public REITs — liquid, correlated with equity markets, high fees, dilute performance across hundreds of positions.
    • Private funds — blind pools, limited transparency, layered fees, long durations.
    • Traditional syndications — single-asset exposure, but often with promote structures that misalign GP and LP incentives.
    • Direct co-investment with a developer — single project, transparent economics, identical terms as the sponsor, distributions at exit.

    Each has a role. Our view is that direct co-investment with a developer who invests its own capital alongside LPs offers the cleanest alignment for accredited investors — because there is no scenario where the sponsor wins if the LPs don’t.

    Tax and legal considerations for U.S. real estate investment

    Direct ownership of U.S. real estate is broadly open to non-U.S. persons. Structures like LLCs, LPs, and (for certain investors) EB-5 pathways provide flexibility. The tax code allows depreciation to offset rental income, and 1031 exchanges permit deferral into like-kind assets. For foreign investors, tax treaties may minimize double taxation on repatriated proceeds — proper legal and tax counsel is essential and should be secured before any capital moves.

    The bottom line on U.S. real estate investment in 2026

    U.S. real estate remains one of the most durable investment categories in the world. But durability isn’t uniformly distributed. In 2026, the highest-conviction opportunity we see is in the coastal South Florida corridor — where structural demand and structural supply constraint have converged in a way that we don’t expect to reverse this decade. And the sponsor question — outsourced GC vs. in-house GC — matters more than most investors realize.

    If you’d like to talk through how any of this applies to your allocation strategy, schedule a 15-minute conversation with Luis Noronha.

    External sources

  • Housing Market Predictions 2025–2029

    Housing Market Predictions

    Housing Market Predictions for Next 5 Years: 2025 to 2029

    The U.S. housing market stands at a pivotal juncture, shaped by a shifting economic landscape, evolving demographics, and technological disruption. With rising interest rates, changing consumer behavior, and a highly dynamic global context, the market outlook for the next five years—from 2025 to 2029—demands deep analysis and precise forecasting. For real estate developers, investors, and housing policy experts, understanding these dynamics will be critical to capitalizing on opportunities and mitigating risks in residential real estate.

    In this post, we explore expert-driven forecasts on home price trends, geographic growth hotspots, demographic influences, rental market trajectories, and risk factors that are likely to influence the U.S. housing market’s evolution through 2029.

    Home Price Trends and Regional Variations

    After a decade of largely bullish trends in housing prices—punctuated briefly by the market corrections of the early 2020s—the next five years are expected to see more nuanced, regionally diverse growth patterns. According to projections by Fannie Mae and the National Association of Realtors, national home price appreciation will moderate to an annual average of 2.5% to 4%, far below the feverish double-digit growth of 2020-2021.

    However, this cooling will not uniformly affect all markets. Sun Belt cities such as Austin, Phoenix, and Tampa, which experienced explosive growth in the 2020s, may face continued price volatility due to affordability issues and overbuilding. In contrast, mid-size metros in the Midwest—think Columbus, Indianapolis, and Minneapolis—are forecast to emerge as more stable markets with steady year-over-year price growth and increased institutional investment interest.

    Housing affordability will also remain an enduring concern. High mortgage rates—projected to hover between 5.5% and 6.5% through 2029—combined with constrained new housing supply in desirable urban and suburban areas, are likely to keep price-to-income ratios well above historical norms. Market analysts predict a sustained inventory shortage, mainly affecting entry-level homes, which may hinder demand despite buyers’ intent.

    Demographic Drivers and Demand Shifts

    From 2025 through 2029, demographic patterns will exert a powerful influence on both housing demand and design. The maturation of Millennial and early Gen Z cohorts into their peak homebuying years promises a significant baseline of demand. Millennials, many of whom postponed homeownership due to student debt and economic instability, will likely drive the market for both single-family homes and urban condos—especially in lifestyle-centric, affordability-advantaged metros.

    Concurrently, Baby Boomers are downsizing at record levels, reshaping inventory flows and property types coming to market. This generational shift opens avenues for developers focusing on active adult and mixed-use communities tailored for aging residents. Expect a growing demand for aging-in-place features, energy efficiency, and smart home technologies in newly built homes targeting older, mobile populations.

    Meanwhile, immigration policy will play a wildcard role. Should immigration rates recover post-2025 due to policy changes or labor market needs, the influx of new residents can buoy demand in both urban rental markets and first-time buyer segments.

    Rental Market Projections and Multifamily Developments

    The rental housing market, after undergoing significant volatility during the COVID-19 era, is projected to strengthen in the second half of the 2020s. Rising interest rates will push more younger consumers into renting for longer durations. Urban centers offering high-wage job clusters, such as Boston, Seattle, and Denver, are expected to see increased renter demand that outpaces residential construction starts, leading to upward pressure on rents.

    According to the Urban Land Institute, multifamily development will remain a top investment arena for institutional investors, increasingly focused on environmentally certified, tech-enabled, and transit-accessible properties. Suburban build-to-rent (BTR) communities—a hybrid between single-family homes and traditional multifamily—are poised for rapid expansion, serving middle-income households priced out of ownership yet seeking space and amenities.

    Land use reform and zoning changes at the municipal level could further accelerate multifamily construction. Cities such as Minneapolis, Portland, and Charlotte have already begun implementing reforms to permit higher-density projects in traditionally single-family zones, paving the way for new development pipelines that align with changing societal norms and sustainability imperatives.

    Technological Disruption and Infrastructure Development

    Technology will continue to reshape the housing development landscape between 2025 and 2029. Proptech innovations—including AI-driven valuation tools, blockchain-enabled property transactions, and digital twin modeling—will enhance project viability analyses, streamline sales, and reduce costs. Automation in construction, like 3D-printed housing components and modular prefabrication, will play pivotal roles in addressing labor shortages and affording faster project timelines.

    Broadband expansion and remote work adoption will also shift geographical demand. Second-tier and “Zoom Town” markets—such as Bozeman, Chattanooga, and Spokane—will thrive as viable alternatives for professionals seeking lifestyle affordability without sacrificing connectivity or amenities. Infrastructure investments authorized under the 2021 Infrastructure Investment and Jobs Act will further catalyze residential development in previously underutilized growth corridors, especially near new transit lines or logistics hubs.

    Key Risks and Market Uncertainties

    No housing market forecast is complete without considering downside scenarios. The most salient risks facing the housing market through 2029 include:

    • Interest Rate Volatility: The possibility of higher-than-expected inflation or sustained monetary tightening could lead to prolonged periods of elevated borrowing costs, reducing affordability and slowing transaction volumes.
    • Geopolitical Disruptions: Global instability—whether from armed conflicts, climate-related migration shocks, or commodity price instability—could reverberate through capital markets and affect construction costs and buyer sentiment.
    • Regulatory Constraints: Housing development continues to be heavily localized, subject to zoning, permitting, and NIMBY opposition. Delayed entitlements, litigation, and construction hurdles will challenge timeline and cost structures, particularly in high-demand urban cores.
    • Climate Risk: Increasingly, climate change is shaping both insurance pricing and development feasibility. Markets vulnerable to hurricanes, wildfires, or water scarcity (e.g., Florida, California, Arizona) may see declining investor appetite, while “climate-resilient” cities could ascend in strategic prominence.

    Investment Opportunities for Developers and Stakeholders

    Despite a moderated growth landscape, opportunities abound for stakeholders who align their strategies with demographic realities, technological shifts, and local policy trends. Key investment themes anticipated between 2025 and 2029 include:

    • Attainable Housing: Developing mid-tier homes with efficient footprints, shared amenities, and affordability incentives will address acute shortages and appeal to underserved segments.
    • Mixed-Use Communities: Projects that integrate housing with retail, wellness, and co-working spaces will thrive in both post-pandemic urban design and aging-in-place scenarios.
    • Green and Healthy Buildings: ESG-focused investors are increasingly demanding carbon-neutral construction, indoor air quality optimization, and renewable energy integration—all poised to become development hygiene factors rather than differentiators.
    • Adaptive Reuse: Converting underutilized commercial stock (office buildings, malls, warehouses) into housing offers lower acquisition costs and aligns with sustainability goals and municipal revitalization programs.

    Conclusion: Navigating a Balanced Yet Dynamic Market

    The next five years in the U.S. housing market will present a more measured pace of growth than the frenetic peaks and valleys of the early 2020s. For real estate professionals, success will hinge on carefully navigating macroeconomic forces, embracing innovative technology, and anticipating shifting consumer preferences. Geographic and strategic differentiation will become increasingly essential as uniform national trends give way to localized cycles based on infrastructure, policy, and climate profile.

    Ultimately, the housing market from 2025 to 2029 promises fewer windfalls, but greater resilience—where those who prioritize long-view planning, sustainability, and adaptability will emerge as the sector’s next-generation leaders.

    External Sources

  • Urban Living Trends: The Future of Real Estate

    Urban Living Trends: The Future of Real Estate

    Urban living trends in real estate

    Introduction

    The real estate market is undergoing a significant transformation driven by evolving consumer preferences, technological advancements, demographic shifts, and the impact of global events. This article examines the current trends in urban living, with a particular focus on the growing demand for sustainable development, mixed-use spaces, and smart home technology. By understanding these trends, investors, developers, and homeowners can make informed decisions in today’s dynamic real estate landscape.

    The Rise of Sustainable Development

    Sustainability has emerged as a critical focus in real estate, with urban dwellers increasingly prioritizing environmentally friendly living spaces. This trend aligns with a broader societal shift toward sustainability as individuals and communities become increasingly aware of the impact of climate change and the importance of reducing their carbon footprints.

    Green Building Practices

    The construction industry is responding to this demand by integrating green building practices into new developments. These practices include utilizing eco-friendly materials, optimizing energy efficiency, and implementing renewable energy sources such as solar panels. According to the U.S. Green Building Council, buildings that adhere to sustainable standards can significantly reduce energy and water consumption, resulting in lower operational costs for both homeowners and tenants.

    Urban Green Spaces

    Moreover, urban planners are increasingly incorporating green spaces into city designs. Parks, green roofs, and community gardens not only enhance aesthetic appeal but also promote mental well-being and community interaction. A study published in the journal “Environmental Science & Technology” indicates that access to green spaces can improve residents’ quality of life, making them a desirable feature in residential developments.

    The Popularity of Mixed-Use Developments

    Another notable trend in the real estate market is the rise of mixed-use developments. These projects integrate residential, commercial, and recreational spaces into a single area, fostering a sense of community and convenience.

    Benefits of Mixed-Use Living

    Mixed-use developments cater to the modern consumer’s desire for walkability and accessibility. As urban populations grow, residents increasingly seek neighborhoods where they can live, work, and play without the need for extensive commuting. This trend is particularly evident in metropolitan areas where traffic congestion and long commutes have become significant concerns.

    Case Studies: Successful Mixed-Use Projects

    Cities such as New York, San Francisco, Miami, and Toronto have seen a surge in mixed-use developments. For instance, the Hudson Yards project in New York City exemplifies how integrating residential, commercial, and public spaces can create a vibrant community hub. Such developments not only attract residents but also enhance local economies by fostering business growth and increasing foot traffic.

    The Influence of Smart Home Technology

    As technology continues to evolve, smart home innovations are becoming increasingly prevalent in the real estate market. Homebuyers are now looking for properties equipped with smart technologies that enhance convenience, security, and energy efficiency.

    Features of Smart Homes

    Smart home technology encompasses devices such as smart thermostats, security systems, lighting controls, and home automation systems that can be remotely managed via smartphones. According to a report by the Consumer Technology Association, nearly 75% of U.S. households own at least one smart home device, indicating a growing consumer preference for tech-enhanced living environments.

    Implications for Real Estate

    For real estate developers, incorporating smart technology into new constructions can significantly increase property value and appeal to tech-savvy buyers. As demand for such features rises, properties equipped with smart technology are likely to command higher prices and attract a broader range of prospective buyers.

    Demographic Shifts and Urbanization

    Demographic trends, particularly the movement of millennials and Gen Z into urban areas, are reshaping the real estate market. Younger generations prioritize experiences over ownership, leading to increased demand for rental properties and smaller living spaces that offer flexibility and access to urban amenities.

    The Impact of Remote Work

    The COVID-19 pandemic has accelerated the shift towards remote work, prompting many individuals to reconsider their living arrangements. With the ability to work from anywhere, some are opting for suburban or rural living, seeking larger homes at lower costs. However, urban centers remain attractive due to their rich cultural offerings, diverse job opportunities, and strong social connectivity.

    Housing Affordability Challenges

    As urban areas continue to experience population growth, housing affordability has become a pressing issue. Many cities are grappling with how to provide affordable housing options while maintaining the character and vibrancy of their neighborhoods. Policymakers and developers are tasked with creating solutions that effectively address both supply and demand.

    Conclusion

    The real estate market is witnessing a profound evolution shaped by sustainability, technological advancements, and demographic shifts. The trends toward sustainable development, mixed-use living, and smart home technology reflect the changing preferences of urban dwellers, who seek convenience and a high quality of life. As these trends continue to develop, stakeholders in the real estate market must adapt their strategies to meet the demands of a new generation of homeowners and renters, ensuring that urban living remains accessible, attractive, and sustainable.

    Sources:
    IoT | Sieze Today. https://siezetoday.com/tag/iot/

    The Future of Composite Materials in Aerospace Industry: Emerging Trends and Innovations – SMI Composites. https://www.smicomposites.com/the-future-of-composite-materials-in-aerospace-industry-emerging-trends-and-innovations/
    Rebecca Wyatt – PARCEL Industry. https://parcelindustry.com/by-author-1507-1.html
    Sustainable Urban Planning: Building Livable Cities for the Future – Geeklybee. https://www.geeklybee.com/sustainable-urban-planning/
    Cao, Y., Song, X., & Wang, T. (2015). Development of an Energy-Aware Intelligent Facility Management System for Campus Facilities. Procedia Engineering. https://doi.org/10.1016/j.proeng.2015.08.446
    U.S. Green Building Council Announces Recipients of 2023 LEED Homes Awards | Weber Thompson. https://www.weberthompson.com/u-s-green-building-council-announces-recipients-of-2023-leed-homes-awards/
    Building Inclusive Cities: A Vision for Accessible and Equitable Urban Development. https://reflections.live/articles/18210/building-inclusive-cities-a-vision-for-accessible-and-equitable-urban-development-article-by-kamakshi-srimal-18923-m3stdvxe.html
    Canadian study finds banned cancer-causing chemicals in 88% of household products. https://health.news/2023-04-26-carcinogens-found-in-88percent-of-household-products.html
    The Current Real Estate Market Trends | CCW Photos. https://ccwphotos.com/29781-the-current-real-estate-market-trends-20/
    9 Trends Defining the Future of Luxury Homes – Luxarc. https://www.luxarc.in/blogs/news/9-trends-defining-the-future-of-luxury-homes
    Transform Your Space: Exploring the Latest Home Decor Trends of 2023 -. https://advantage1mtg.com/3452/transform-your-space-exploring-the-latest-home-decor-trends-of-2023
    Top 7 Features of Smart Homes Creating Trends in Real Estate | Elliot Adler. https://elliotadler.bravesites.com/entries/general/Top-7-Features-of-Smart-Homes-Creating-Trends-in-Real-Estate
    Nine Home Improvements to Modernize a Fixer-Upper – Merriment Maker by Uncustomary. https://uncustomary.org/nine-home-improvements-to-modernize-a-fixer-upper/
    Advanced Television | Tag Archive | nextgen. https://advanced-television.com/tag/nextgen/
    Why Build a Private Guest House on Your Property?. https://eastonhomes.com/blog/why-build-private-guest-house/
    (2023). Recognizing Excellence: Women in Secured Finance Profiles. The Secured Lender, 79(2), 14-16,18.
    Techsalerator. https://www.techsalerator.com/use-cases/urban-planning-and-infrastructure-development
    Technology Trends Transforming Freight Operations. https://www.technologytimesnow.com/technology-trends-transforming-freight-operations/

  • The One Big Beautiful Bill Boosts Impact for Real Estate Investors

    In mid-2025, Congress introduced what’s being called the One Big Beautiful Bill—a sweeping tax reform package aimed at reigniting economic growth, incentivizing investment, and easing burdens on individuals and businesses alike. For real estate investors and developers, this legislation represents more than just another tax cut—it is a potential game-changer.

    With targeted provisions benefiting property developers, syndicators, and even passive investors, the bill’s real estate-friendly measures offer new tools to boost profitability, unlock liquidity, and optimize long-term strategies. In this article, we’ll unpack the most relevant parts of the bill and explain how each can positively affect real estate investing in the coming years.

    1. 100% Bonus Depreciation Extended (and Expanded)

    One of the most powerful tools in the investor’s tax toolbox is bonus depreciation, and the Big Beautiful Tax Cut gives it a significant revival. Originally set to phase out after 2026, the bill extends 100% bonus depreciation through 2029. Even more significantly, it expands the list of eligible property and reintroduces enhanced Section 179 expensing limits, raising the cap to $2.5 million (phasing out at $4 million).

    Why This Matters:

    For developers and property owners, bonus depreciation allows for immediate deduction of the full cost of qualifying improvements, such as appliances, HVAC systems, roofing, and other building components. Typically, these items would be depreciated over 5, 15, or even 39 years.

    By deducting them in the first year, investors can significantly reduce taxable income, improving short-term cash flow and increasing the internal rate of return (IRR). This is especially impactful for value-add projects or new developments where heavy capital expenditures occur early in the investment cycle.

    Practical Example:

    Suppose a developer spends $600,000 on qualified improvements across a portfolio of rental properties. In that case, they can deduct that full amount in the first year rather than over decades, saving as much as $200,000 in taxes depending on their tax bracket.

    2. SALT Deduction Cap Raised

    The bill loosens the controversial State and Local Tax (SALT) deduction cap introduced in the 2017 Tax Cuts and Jobs Act. That law limited SALT deductions to $10,000, disproportionately hurting taxpayers in high-cost states like New York, California, and Florida. The new legislation raises the cap significantly, to $30,000 or even $40,000, depending on the version of the bill and income levels.

    Why This Matters:

    Real estate professionals and high-net-worth individuals who invest through pass-through entities often report their income on personal returns. The new SALT deduction cap offers meaningful relief—especially for investors based in high-tax states—by allowing more of their state and local taxes to be deducted at the federal level, thereby reducing overall taxable income.

    Investor Takeaway:

    With larger SALT deductions, net after-tax returns improve. For sponsors marketing high-end or urban projects, this also improves the financial picture for potential investors deciding between asset classes.

    3. Qualified Business Income (QBI) Deduction Improved

    The QBI deduction under Section 199A has been a significant benefit for investors and developers operating through LLCs, S corporations, or partnerships. The Big Beautiful Tax Cut increases this deduction from 20% to 23% of qualified business income after 2025.

    Why This Matters:

    A higher QBI deduction increases the effective return for investors who receive income from rental activities classified as a qualified trade or business. This extra 3% might seem minor, but it adds up, especially for those with seven- or eight-figure income from real estate operations.

    Strategic Implication:

    Sponsors should consider revisiting their entity structures to maximize QBI eligibility, especially for joint ventures and development deals where income distributions can be optimized.

    4. Opportunity Zones Extended with Enhancements

    Initially established in 2017, Opportunity Zones (OZs) have driven billions in investment into underserved communities. The Big Beautiful Tax Cut extends the OZ program through 2033. It introduces enhancements aimed at rural areas, as well as long-term holding benefits.

    Key updates include:

    • 30% basis step-up after 5 years (up from 10% at 5 years previously) for rural OZs
    • Expanded eligibility for zones in tribal and economically distressed areas
    • Greater clarity on reporting and compliance requirements

    Why This Matters:

    The enhancements create a fresh incentive for developers to look outside major metros for projects in rural or emerging markets. Investors get greater tax deferral and permanent capital gains exclusion benefits for qualified OZ investments.

    Long-Term View:

    For firms with experience in secondary markets, this presents an excellent opportunity to pursue affordable housing, hospitality, or mixed-use projects in underutilized areas, now with enhanced tax incentives to support them.

    5. Enhanced Low-Income Housing Tax Credit (LIHTC)

    Affordable housing developers have long relied on the LIHTC to bring equity into deals that may otherwise be financially infeasible. The new tax law increases the 9% credit allocation by 12.5% from 2026 to 2029 and reduces the 4% credit bond-financing threshold from 50% to 25%.

    Why This Matters:

    These changes make it easier to qualify and raise capital for LIHTC-funded projects. Developers working on affordable or mixed-income housing can now access larger equity contributions from syndicators or institutional partners.

    The 25% bond financing threshold makes it easier for smaller or more complex projects to get approved, reducing project delays and allowing for faster execution.

    6. Passive Activity and Business Interest Deduction Clarifications

    The bill also refines the business interest expense limitation rules under Section 163(j), reintroducing the ability to add back depreciation and amortization, at least through 2029.

    Additionally, the excess business loss limitations for non-corporate taxpayers were retained but clarified in favor of certain real estate activities.

    Why This Matters:

    Investors using leverage as a growth tool will benefit from more favorable treatment of interest expense, especially in capital-intensive development or syndication structures. The ability to fully deduct interest improves project feasibility and post-tax returns.

    7. New Withholding Rules for Foreign Investors

    Foreign investors play a critical role in U.S. real estate, particularly in gateway cities and large-scale commercial developments. The new bill introduces withholding requirements ranging from 5% to 20% on capital repatriation from certain U.S. real estate investments.

    Why This Matters:

    While this introduces more administrative work and potential delays in repatriation, it also increases regulatory clarity. For developers working with foreign limited partners (LPs), the new withholding rules can be built into the project’s waterfall and modeled accordingly.

    It’s essential to note that these provisions do not eliminate the appeal of U.S. real estate for international investors. The U.S. remains a stable, appreciating, and dollar-denominated market, now with more explicit rules for taxation and compliance.

    Final Thoughts: A Golden Window for Real Estate Investment

    While the political future of the bill remains uncertain, one thing is clear: the tax code is leaning in favor of real estate, and savvy investors should act accordingly. Whether it’s capturing faster depreciation, unlocking capital in Opportunity Zones, or restructuring pass-through entities to maximize deductions, the legislation offers a compelling case for reassessing strategy.

    Of course, it’s not without complexity. Developers and investors will need to work closely with tax advisors, legal counsel, and underwriters to ensure full compliance and maximize the benefit of each provision.

    However, overall, the Big Beautiful Tax Cut presents real estate professionals with a rare opportunity to increase after-tax returns, access new capital, and expand into previously underutilized markets. With the right structure and timing, the benefits could echo throughout the next investment cycle.

  • The Impact of Remote Work on the Real Estate Market

    The Impact of Remote Work on the Real Estate Market

    The rise of remote work

    Introduction

    The COVID-19 pandemic has markedly shifted our professional and personal lives, with one of the most significant changes being the widespread adoption of remote work. This shift has not only altered the dynamics of where and how work is conducted but has also had profound implications for the real estate market. As companies reevaluate their operational strategies and employees reconsider their living arrangements, the real estate landscape is undergoing a transformation that warrants a thorough exploration.

    The Growth of Remote Work

    According to a report by McKinsey & Company, nearly 20 to 25 percent of the workforce in advanced economies could continue to work remotely three to five days a week without losing productivity. This shift towards remote work has been further corroborated by a survey from Buffer, which indicated that 97% of remote workers would prefer to work remotely at least some of the time for the rest of their careers. These statistics underscore a significant behavioral change in the workforce, suggesting that remote work is not merely a temporary solution but a long-term trend.

    The Impact on Urban Real Estate

    As employees embrace the flexibility that remote work affords, many are reconsidering their living situations. Urban areas, once the epicenter of employment opportunities, are witnessing a decline in demand for residential properties. High-density cities, characterized by their premium housing markets and high cost of living, have experienced an exodus of residents seeking more spacious and affordable living conditions in suburban or rural areas. For instance, cities like New York and San Francisco have seen significant decreases in rental prices as vacancies rise due to this trend.

    This shift has prompted real estate developers and investors to re-evaluate their strategies. Properties in suburban areas are gaining traction, with a marked increase in demand for single-family homes that offer ample space for home offices and outdoor amenities. The National Association of Realtors reported that sales of suburban homes have surged, indicating a robust market for properties that cater to the needs of remote workers.

    The Suburban Surge

    In response to the growing interest in suburban living, real estate developers are pivoting towards creating communities that cater to remote workers. These developments often feature home offices, high-speed internet access, and community amenities such as parks and recreational facilities. The emphasis on lifestyle has become paramount, with many buyers prioritizing quality of life over proximity to urban job centers.

    The Influence on Commercial Real Estate

    The repercussions of remote work extend beyond residential properties to commercial real estate as well. With companies adopting flexible work arrangements, the demand for traditional office spaces has diminished. Many organizations are rethinking their office footprint, opting for hybrid models that require less physical space. As a result, commercial landlords are faced with rising vacancy rates and the need to adapt to a changing market.

    In an effort to remain competitive, commercial real estate owners are exploring innovative solutions to attract tenants. This includes redesigning office spaces to accommodate collaborative environments, incorporating health and safety features, and offering flexible leasing options. Additionally, as the demand for remote work increases, the need for coworking spaces and shared offices is also on the rise, presenting new opportunities in the commercial real estate sector.

    The Role of Technology

    The evolution of the real estate market in the age of remote work is also significantly influenced by technology. Virtual tours, digital transactions, and advanced data analytics are reshaping how properties are marketed and sold. The ability to conduct transactions online has made it easier for buyers to explore properties without the constraints of geography, further fueling the demand for suburban and rural homes.

    Technological advancements are also enhancing the home-buying experience. Platforms such as Zillow and Redfin provide buyers with a wealth of information about listings, neighborhood statistics, and market trends. Furthermore, the integration of artificial intelligence in the real estate sector is improving property valuation, predictive analytics, and customer service, ensuring that both buyers and sellers can navigate the market effectively.

    Challenges and Considerations

    Despite the optimistic outlook for the real estate market driven by remote work, several challenges remain. The economic uncertainty stemming from the pandemic could impact buyer confidence and lending practices. Additionally, the long-term sustainability of remote work remains to be seen, as organizations may eventually pivot back to in-office operations.

    Moreover, the rapid changes in the housing market could exacerbate issues of affordability and access. As demand for suburban homes rises, there is a risk that prices will escalate beyond the reach of many potential buyers. Policymakers and industry stakeholders must address these challenges to ensure that the benefits of this transformation are equitably distributed.

    Conclusion

    The rise of remote work has catalyzed a significant transformation in the real estate market, influencing both residential and commercial sectors. As individuals and organizations adapt to new ways of working and living, the demand for real estate is evolving in tandem. The shift towards suburban living, the reimagining of commercial spaces, and the integration of technology are all shaping the future of real estate in profound ways.

    As we move forward, it will be crucial for industry stakeholders to remain attuned to these trends and adapt their strategies accordingly. While challenges persist, the opportunities presented by the changing landscape of work and living arrangements are substantial. Embracing these changes will be essential for success in the dynamic world of real estate.

    #realestate #remotework #housingmarket #commercialrealestate #suburbanliving #homebuying #propertytrends #realestateinvesting #realestateinvestor

    Sources:

    How COVID-19 Changed the Workplace Forever
    Post-Pandemic Trends in Real Estate
    Remote Work Productivity Statistics and Insights
    Future of Work: Remote, Hybrid, and In-Office Models
    Urban Exodus: Why People Are Leaving Cities
    Affordable Housing Trends in Suburban Areas
    Top Features Buyers Look for in a Remote Work Home
    Suburban Development Projects: A New Frontier for Real Estate Investors
    The Decline of Traditional Office Spaces: What’s Next?
    Coworking Spaces: The Future of Flexible Work Environments
    The Impact of Technology on Real Estate Sales and Marketing
    The Affordability Crisis in Suburban Real Estate
    How Economic Uncertainty Affects the Housing Market
    Emerging Real Estate Trends to Watch in 2025
    Adapting Real Estate Strategies for a Remote-First World